Community, Diversity, Sustainability and other Overused Words

Community, Diversity, Sustainability and other Overused Words
Will we continue to be able to buy homeowners insurance in a state with floods, fires and earthquakes? Your vote for insurance commissioner will decide.
Vote Ben Allen for Insurance Commissioner: Experience, Results, and a Plan That Can Actually Work
Vote Ben Allen for Insurance Commissioner: Experience, Results, and a Plan That Can Actually Work
California's homeowners insurance market is in crisis. Carriers have restricted new business, premiums have soared, the FAIR Plan has ballooned, and too many disaster survivors still wait too long for fair payment. The next commissioner will decide whether we stabilize that market or gamble it on an untested experiment.
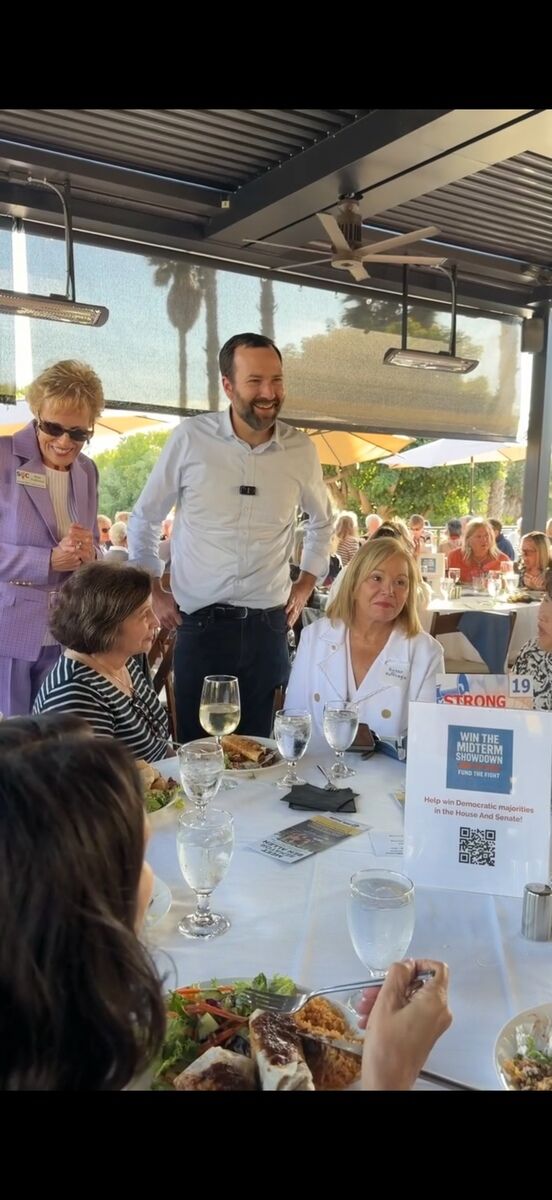
I have known Ben Allen since he was a kid in Santa Monica. He grew up here, served on the Santa Monica-Malibu school board, and has represented this community in the State Senate for more than a decade. After the Palisades Fire tore through his district, he did what a serious legislator does: he wrote bills, pressed insurers, and pushed for faster help for people who had lost everything. That record-not slogans-is why Californians should elect him Insurance Commissioner on November 3.
Vote Ben Allen for Insurance Commissioner: Experience, Results, and a Plan That Can Actually Work
Allen's approach is grounded in work he has already done. He authored SB 495, which requires insurers to make significant upfront payments for personal property losses instead of forcing fire victims to itemize every destroyed item first. He helped put the $10 billion climate and wildfire-prevention bond on the 2024 ballot-and voters approved it. He chairs the Senate Budget Subcommittee on Environmental Protection and Energy. He has spent years on consumer protection, transparency, and climate resilience-the exact portfolio of the Department of Insurance. After the 2025 fires, he has been in the rooms where claims delays, underinsurance, and market flight were not abstractions.
Jane Kim, the former San Francisco supervisor who finished first in the June primary, offers a different product: "natural disaster insurance for all," a state-run pool she analogizes to programs in New Zealand, France, and Spain. The comparison does not hold. Those systems do not cover fire the way she implies; New Zealand's program, for example, provides capped first-layer coverage for certain rare hazards and leaves fire to private insurers. Kim has not produced a white paper, a price tag, or a credible capitalization plan for a fund that would have to absorb California-scale wildfire losses. Even some consumer advocates have questioned whether such a fund could survive one bad fire season without dumping tens of billions onto taxpayers.
Her campaign has also stretched facts. She has spoken as if California does not already restrict insurer profits and as if credit scores can still be used to deny coverage here-both already prohibited. In interviews she has struggled to answer a basic question about her own insurance experience, pivoting instead to general advocacy credentials. The insurance commissioner is a consumer-watchdog job, but it is also a technical regulatory job that requires command of rate filings, solvency, claims handling, and market conduct. Political talent is not a substitute for that command.
Kim's San Francisco record includes real accomplishments on wages and community college. It also includes an ethics complaint over her work opposing a SoMa housing project while paid by a related nonprofit, and an earlier campaign-finance stipulation for using candidate-committee funds on a ballot-measure ad. Voters can weigh those facts themselves. What they should not ignore is the mismatch between her signature proposal and the actual mechanics of California's insurance market.
Allen has pledged not to take insurance-industry money and has a long legislative record of taking on utilities, oil, and other entrenched interests. He wants to staff the Department of Insurance so it can actually answer the phone, speed rate reviews, reward verified home-hardening and mitigation, and pull people off the FAIR Plan by making the private market function again. That is reform, not replacement of the entire system with an unfunded state monopoly. The California Democratic Party, both of California's U.S. senators, and newspapers that have looked closely at the proposals have concluded the same thing.
Homeownership, rebuilding after disaster, and the ability to buy or sell a house without an insurance veto are not ideological talking points. They are bread-and-butter realities for millions of Californians. Ben Allen has already legislated on those realities. Jane Kim has offered a vision that sounds bold until you ask how it is paid for, how it treats fire risk, and whether it would drive more carriers out rather than bring them back.
I watched Ben Allen learn this community as the youngest person ever to serve on the SMMUSD board, then the youngest person elected to the California Senate in 100 years. He is a person of extra-ordinary talents and integrity.
I have watched him legislate through the worst fire season our region has seen. California needs a commissioner who has already done the hard work-not one who is still explaining why the job is "political" rather than showing he or she can run the agency. Vote Ben Allen.


Reader Comments(0)